Rosemeyer Management Group
October 2026 Market Snapshot

October in Review
Developed markets took a slight step back in October with a stark rotation beneath the headline returns with value outperforming growth. The value-heavy Dow advanced by almost 2% while the tech-heavy Nasdaq retreated by almost 6% for the month. This evidenced a movement of capital from the tech sector to defensive sectors like healthcare, energy, and consumer staples as investors reigned in their optimism on the artificial intelligence (AI) buildout. Led by an emerging market skepticism, international stocks lost almost 3% for the month. Conversely, U.S. bonds experienced their strongest month of 2026 (+2.44% in October) as investors rotated to safe-haven assets even as inflation and oil prices continue to place upward pressure on bond yields.
| Index | 1 Month | YTD |
|---|---|---|
| Dow Jones Industrial Average | 1.76% | 9.08% |
| Standard & Poor’s 500 Average | -0.87% | 11.77% |
| Russell 2000 (Small Cap Index) | 0.58% | 14.37% |
| Total U.S. Stock Market | -0.55% | 11.14% |
| MSCI ACWI ex USA (Intl. Index) | -2.81% | 11.01% |
| Barclay’s U.S. Agg. Bond Index | 2.44% | -0.54% |
Looking Forward
October was a good reminder of the benefits of a diversified portfolio. Gains in bonds offset declines in equities, while losses in growth stocks were offset by positive returns in value stocks. Furthermore, the equal-weighted S&P 500 grew by 5.0% while the headline index lost 0.9% for the month. This strength across a wide array of sectors demonstrated that any technology weakness need not hinder the success of the broader market. Fixed income assets will look to build on a strong month moving forward even as yields remain elevated. The Federal Reserve opted to keep their target interest rate unchanged in their October meeting. Fed Chair Warsh indicated a measured approach to rate hikes as the committee monitors both resilient economic growth and stubborn oil prices continuing to hover around $100/barrel. Meanwhile, markets brace for the U.S. midterm elections. Regardless of election outcome, the S&P 500 typically experiences volatility in the weeks following a midterm election. However, this volatility is typically short-lived and followed by strong returns with the S&P 500 never having been negative 12 months following a midterm election. While this is no guarantee of strong performance, history is certainly encouraging!
On a Personal Note
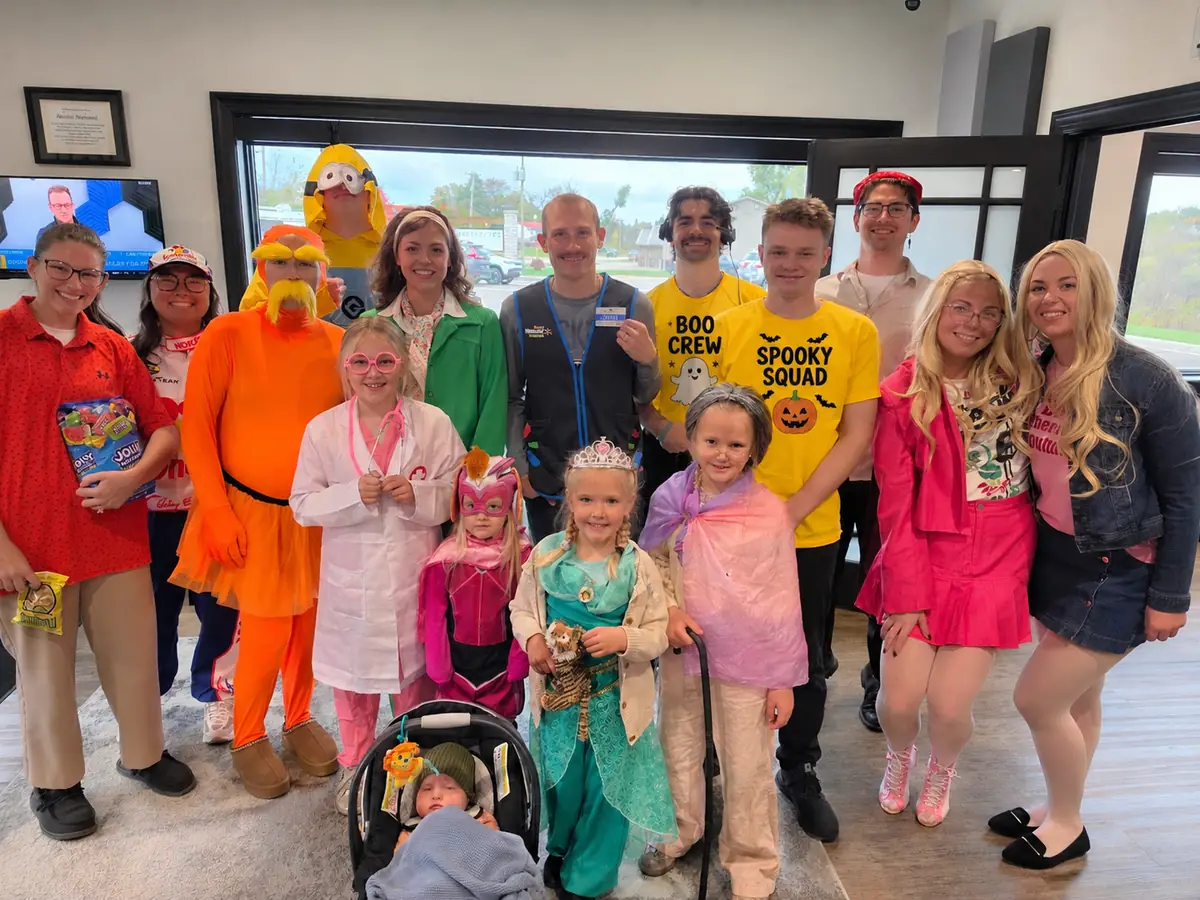
Members of our staff (along with Jacob’s children) went all out to dress up for Halloween in our office this past week. The Lorax even made a surprise appearance! We hope you and your loved ones were able to enjoy the Halloween festivities, and we wish you all well as we approach the coming holiday seasons!
Rosemeyer Management Group
Investment Advisory Services offered through RMG Wealth Management, LLC. Licensed in CO, FL, IA, IL, MA, MN, MO, MT, NV, NY, WA, WI, WV & TX.
i JPMorgan Asset Management, November 2, 2026; Investing.com, November 3, 2026
Past performance doesn’t guarantee future results. The views and material presented in these materials were created and intended to provide background assistance and education. No product or service is offered in connection with the dissemination of this information, and no recommendation regarding the purchase or sale of any security is made, intended or should be implied by these materials.
