Rosemeyer Management Group
August 2026 Market Snapshot

August in Review
Global stock markets resumed their ascent in the month of August. Blockbuster earnings from Nvidia closed out a strong Q2 corporate earnings season that pushed equities higher. Both U.S. and international markets advanced 2-3% for the month. Technology companies rebounded from their July selloff with the Nasdaq returning 4.2%, but surprisingly it was the software sector that led the recovery despite fears that the artificial intelligence (AI) buildout would harm software profitability. In fixed income markets, US bonds returned 0.39% amidst a flattening yield curve. A hawkish speech from new Fed Chair Kevin Warsh drove short-term yields higher while the Treasury buyback of long-dated bonds drove long-term yields lower.
| Index | 1 Month | YTD |
|---|---|---|
| Dow Jones Industrial Average | 1.47% | 11.79% |
| Standard & Poor’s 500 Average | 2.72% | 13.14% |
| Russell 2000 (Small Cap Index) | 0.98% | 20.01% |
| Total U.S. Stock Market | 2.68% | 12.90% |
| MSCI ACWI ex USA (Intl. Index) | 2.57% | 17.01% |
| Barclay’s U.S. Agg. Bond Index | 0.39% | -0.31% |
Looking Forward
Equity investors have largely looked past geopolitical tensions and the release of “economic D-day” in recent weeks, however the opening of the Strait of Hormuz would likely buoy markets while drastically increased hostilities could spook markets. Fed Chair Kevin Warsh noted in his recent Jackson Hole Symposium speech that inflation concerns are likely to remain “higher for longer.” This outlook pushed short-term treasury yields higher. The Treasury Department also announced they will begin buying back 10- and 30-year notes to support treasury market liquidity on September 9th, which softened long-term yields. With a flattened yield curve, this adds another complication to the Fed’s near-term policy route. Odds of an interest rate hike in September have accordingly increased from 36% to 67%. In positive news, economic resiliency continues as Q3 GDP is tracking at 4.61% – double the original 2.4% Bloomberg consensus. Furthermore, the Composite Purchase Managers’ Index (PMI) is sitting at a 52-month high, indicating continued business expansion at a pace well above historical averages. Markets have been driven higher by these robust economic fundamentals, but investors will continue to digest ongoing news as we enter September – a historically poor month for the stock market.
On a Personal Note
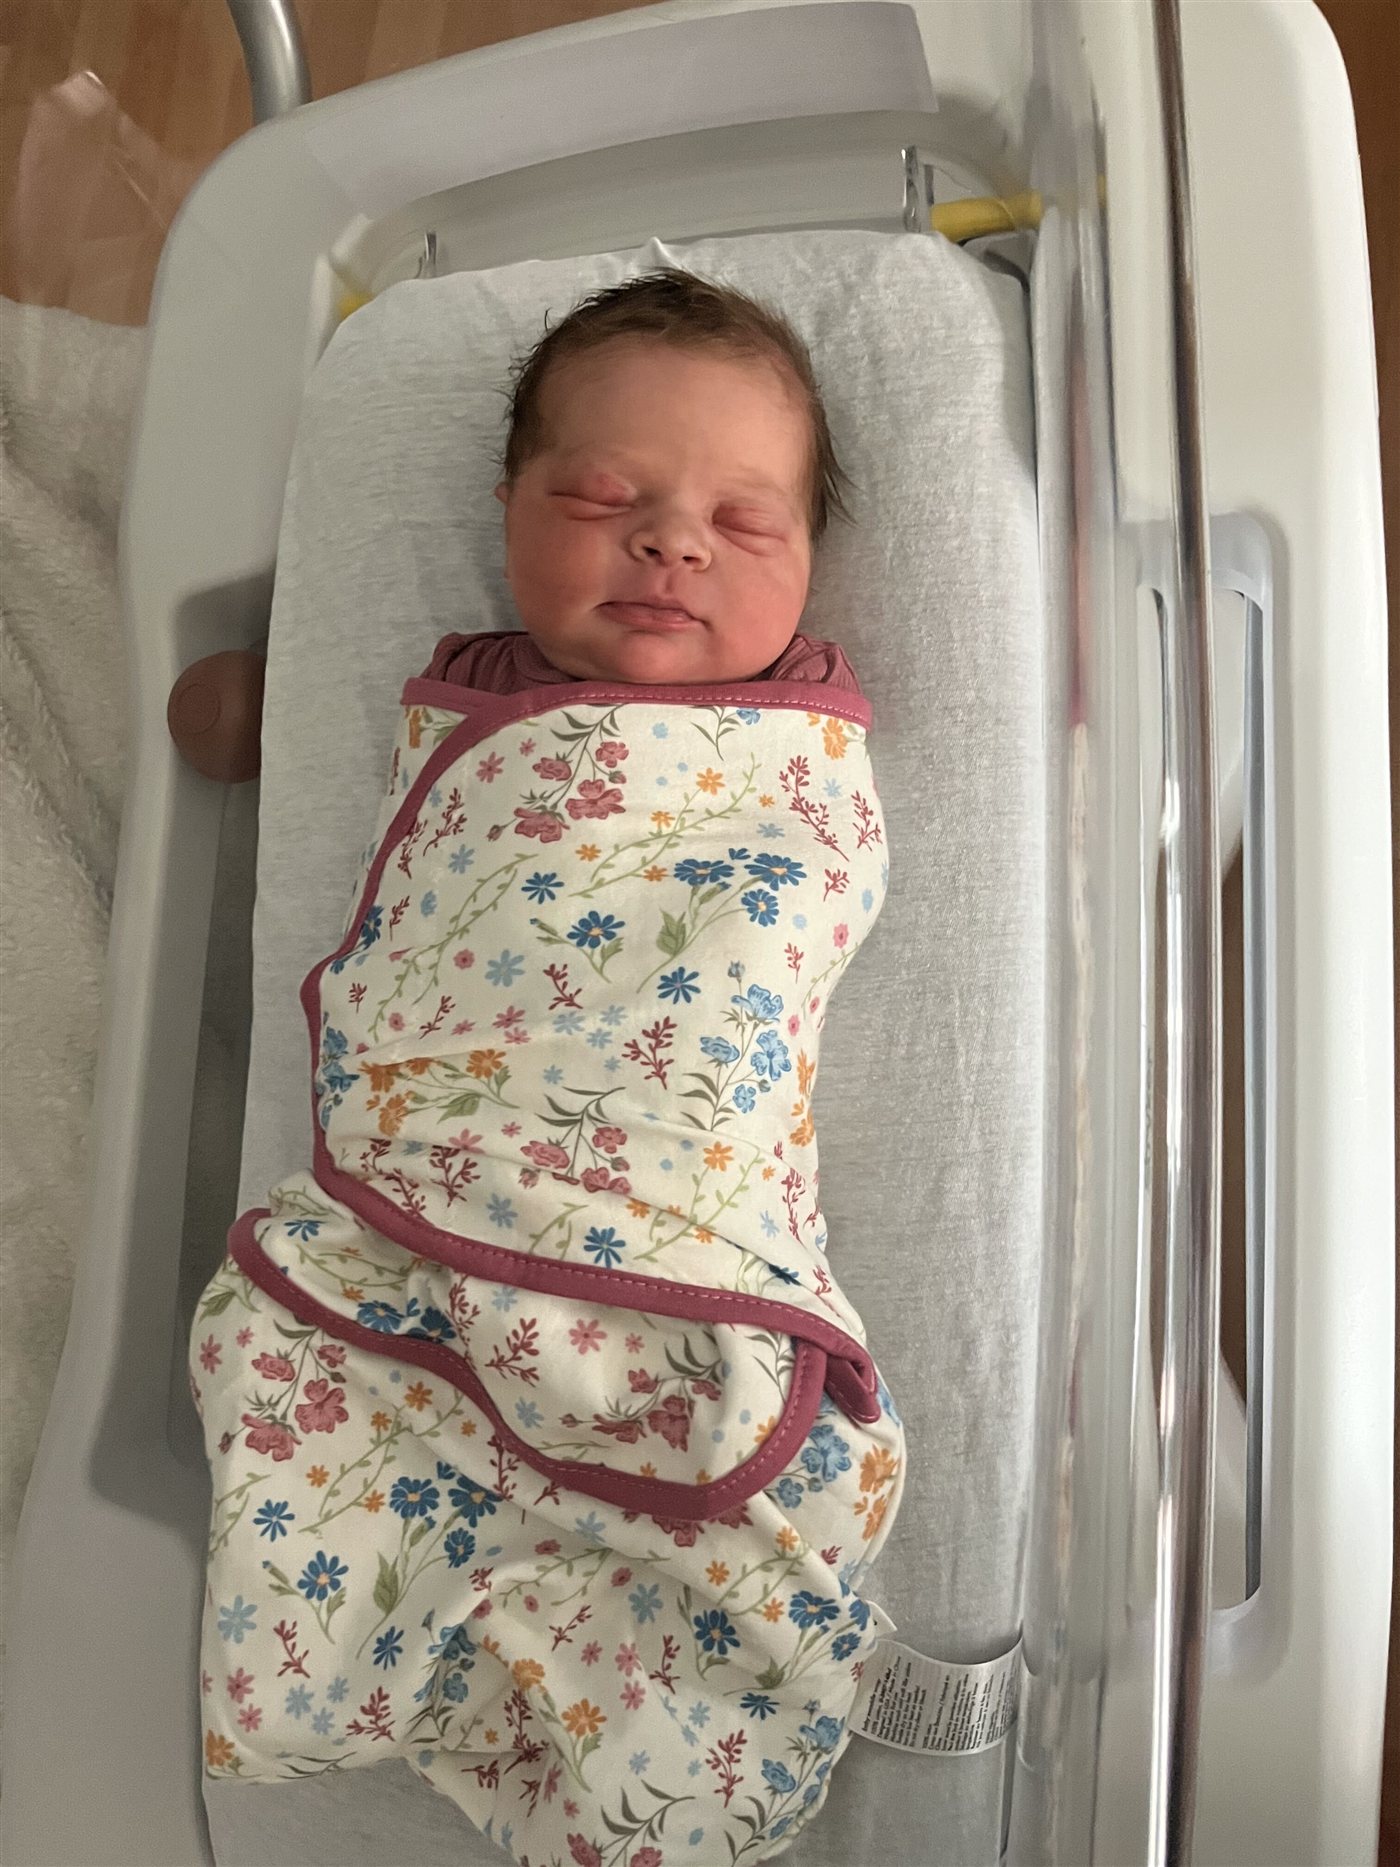
Bryan and Haley Herr welcomed their daughter, Ella Bernadette Herr, on August 15th. Ella weighed 8 lbs. 5 oz. and measured 22.5 inches long. She is already so loved and joins her proud big brother, Hudson. Mom and baby are both doing well, and the entire family is enjoying this special time together as they welcome their newest addition. We hope the beautiful graces of family life continue to bless the Herrs as their family grows!
Rosemeyer Management Group
Investment Advisory Services offered through RMG Wealth Management, LLC. Licensed in CO, FL, IA, IL, MA, MN, MO, MT, NV, NY, WA, WI, WV & TX.
i JPMorgan Asset Management, September 1, 2026; Nasdaq.com, September 1, 2026
Past performance doesn’t guarantee future results. The views and material presented in these materials were created and intended to provide background assistance and education. No product or service is offered in connection with the dissemination of this information, and no recommendation regarding the purchase or sale of any security is made, intended or should be implied by these materials.
